Digital asset markets operate under constant price fluctuations. Participants seek shelter in assets designed to hold a steady unit of account. This pursuit of stability created an entire sector of tokens tied to fiat currencies. Observers frequently ask how do stablecoins maintain their peg when the broader crypto economy experiences severe turbulence. The answer lies in the assets held in reserve by the issuer. When capital preservation becomes the primary objective for traders and institutions alike, the exact nature of those backing assets assumes critical importance. Modern financial systems depend on predictable liquidity, making the underlying architecture of digital currency reserves a matter of intense macroeconomic scrutiny.
Table of Contents
ToggleReserve Composition and Collateralization Mechanics
Fiat-backed stablecoins rely on direct collateralization with cash and cash equivalents. Unlike older iterations that attempted algorithmic stabilization through supply adjustments, fiat-backed variants tie each circulating token to a tangible dollar or equivalent asset. This structural distinction sets the baseline for stablecoin stability across multiple market cycles. Confidence persists only as long as market participants trust that every single token can be redeemed at face value without friction or delay. Central banks and commercial lenders monitor these mechanisms closely, recognizing that digital tokens anchored to sovereign currency influence broader credit conditions and short-term debt markets.
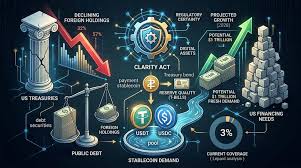
Adequate asset protection is only part of the equation. The specific mix of those assets defines the true risk profile of any given token. Reserve composition typically leans heavily toward short-term treasuries, commercial paper, or overnight repurchase agreements. Academic research published by financial economists indicates that major stablecoin issuers hold enough short-term sovereign debt to rival traditional money market funds. This massive footprint in government debt links digital asset liquidity directly to national monetary plumbing. Economists evaluate these holdings to measure potential systemic spillovers should sudden redemption pressure force issuers into rapid asset liquidations.
Custody of Reserve Assets
Custody of reserve assets determines whether those funds remain accessible during a liquidity crisis. When an issuer relies on multiple banking partners rather than a single institution, the risk of total operational paralysis drops significantly. Transparency regarding where funds sit and who holds the keys prevents the type of blind spots that historically triggered bank runs. Market observers constantly track stablecoin reserves to catch early signs of asset degradation or risky return-seeking behavior by issuers. Protection of these funds requires institutional-grade custody solutions that isolate customer capital from corporate operating accounts.
Verification Standards: Attestation vs. Full Audit
Verification of vault contents requires verifiable proof. Issuers routinely publish periodic reports to demonstrate solvency. A common point of confusion involves what is the difference between a stablecoin attestation and an audit. An attestation provides a limited-scope verification of reserve balances on a specific date. By contrast, a full financial statement audit covers internal controls, operational practices, and financial health across an entire fiscal period. Analysis of these structural divergences helps market participants evaluate the genuine degree of financial protection supporting their digital holdings.
The debate surrounding attestation vs. full audit highlights a persistent compromise in the digital asset sector. Monthly proof of reserves offers timely snapshots of backing assets, but it lacks the deep diagnostic rigor of an independent financial audit. Financial analysts note that attestations can miss internal control vulnerabilities that develop between reporting dates. Regulatory bodies now push for standardized stablecoin auditing standards to close this gap and protect retail and institutional holders alike. Independent accountants play a pivotal role in establishing credibility, ensuring that reported figures align with actual account balances held at licensed depository institutions.
Enterprise Infrastructure and Settlement Rails
Global transfer of digital tokens across ledgers requires robust technological plumbing. Enterprises adopting blockchain rails need dependable infrastructure to manage treasury operations and cross-border settlements. Reliable stablecoin payment solutions provide the necessary middleware to bridge legacy banking systems with decentralized networks, allowing businesses to execute instantaneous transactions without exposing corporate treasuries to native crypto volatility. These integration tools handle automated routing, compliance checks, and multi-chain liquidity management, ensuring that commercial entities can utilize digital dollars safely at scale. Organizations deploying these systems benefit from reduced settlement friction, lower transaction costs, and automated reconciliation that operates around the clock. Enterprise adoption relies heavily on these stable payment layers to eliminate settlement risk and optimize global trade operations.
Structural Risks and Peg Resilience
Market history demonstrates a stark contrast when evaluating fiat-backed vs. algorithmic stablecoins. Fiat-backed assets derive their value from external collateral held in traditional financial custody. Algorithmic alternatives attempt to maintain value through automated code, variable supply mechanisms, and speculative game theory. Past market crashes proved that code alone cannot substitute for real-world cash equivalents during extreme liquidity shocks. When panic sets in, algorithmic designs often spiral into terminal depegging events, wiping out billions of dollars in value within hours. This historical precedent forces modern developers and regulators to prioritize collateralized models over automated experiments.
This fundamental divergence influences how institutional capital flows into the space. Regulated vs. unregulated stablecoin issuers face entirely different compliance burdens and capital reserve requirements. Jurisdictions across the globe now enforce strict rules regarding redemption rights and asset segregation. Holders demand clear legal guarantees that their tokens represent direct claims on underlying reserves rather than unsecured debt issued by offshore entities operating in legal gray areas. Compliance protocols now dictate market access, rewarding entities that maintain open communication channels with banking supervisors.
Regulatory Oversight and Market Integrity
Official oversight has transformed from a distant threat into an active architectural force. Stablecoin regulation creates standardized boundaries for reserve transparency, forcing issuers to abandon opaque accounting practices. Independent reserve audits conducted by recognized accounting firms add a layer of credibility that voluntary disclosures cannot match. Token holders benefit when regulatory compliance aligns with rigorous on-chain tracking, creating a multi-layered defense against insolvency. Public policy discussions increasingly focus on harmonizing cross-border rules to prevent regulatory arbitrage among token issuers.
Core Benchmarks for Peg Stability
Operational integrity relies on clear structural commitments. Several core factors influence current market standards:
- Regular publication of attestation reports verifying one-to-one backing ratios.
- Enforcement of strict redemption rights for all verified token holders.
- Exclusion of risky commercial paper in favor of short-term treasuries.
Analysis of stablecoins vs. volatile cryptocurrencies reveals why digital tokens designed for stability occupy a unique financial category. Bitcoin and similar assets function as speculative stores of value or decentralized commodities. Stablecoins serve as transactional bridges and safe havens during periods of acute market stress. Preserving that functional distinction requires unyielding adherence to transparency standards and conservative reserve management. Market participants rely on this stability to execute arbitrage, provide liquidity, and hedge against localized inflation pressures.
Future stability depends heavily on how issuers adapt to tightening global oversight. Market participants no longer accept vague assertions of solvency without cryptographic and legal backing. Transparency is no longer an optional marketing feature; it remains the absolute foundation upon which modern digital liquidity rests. As regulatory frameworks mature, the institutions that survive will be those that adopt complete openness regarding their balance sheets and reserve practices. Long-term viability in digital finance belongs entirely to entities that treat capital preservation as an absolute operational imperative rather than a secondary compliance checklist.